Fringe 2010: Cactus – The seduction…

This energetic and engaging one man show is definitely a lot of fun. Jonno Katz combines the script with improvised interaction with the audience, accompanying his amusing portrayal of varied characters with the physical comedy that is the highlight of the show.

The show might seem minimalist, with one actor, one costume, simple lighting, little music, and no props – but Katz brings more than enough character and energy to make it feel well furnished.

Definitely recommended, though perhaps not for those who are offended easily by references to romance or sex.

ArtBank

This evening, I visited ArtBank – an institution of the Canada Council for the Arts that has been buying Canadian artworks since the 1970s and then renting them to government offices and private organizations.

The art is rented at 10% of its appraised price, for each year. The minimum term is two years, and the minimum annual expenditure per renting organization is $2,000. The price per work is capped at $3,600, meaning that some of the most valuable pieces are quite a deal to rent. For government offices, the necessary insurance is already in place. Private organizations need to provide written documentation of adequate insurance.

The collection includes 18,000 paintings, prints, photographs and sculptures by over 2500 artists. Sizes range from modest to gigantic. All told, it seems like a rather good resource. It’s certainly a place worth visiting, if the opportunity arises.

Liberal-NDP cooperation

Michael Ignatieff’s ever-wavering stance on cooperation with the NDP is increasingly annoying for me. Sometimes, he seems to think some sort of coalition (with or without support from the Bloc) could be a possibility, at other times he denouces the idea as ‘ridiculous.’ Regardless of which Canadian political parties a person supports, this sort of vacillation seems both muddled and opportunistic (since the coalition looks best when it seems most plausibly in reach). Regardless of political affiliation, it also seems increasingly clear that Ignatieff doesn’t really understand the fix his party is in, or how to get out of it.

I think it should be obvious enough to Canadians that the idea of a merger or coalition between the Liberals and NDP is not ridiculous, from the perspective of those who want there to be a serious opposition challenge to the current government. The effort to ‘unite the right’ by merging the Conservative and Alliance parties has been successful. Now, even though they have a minority of support, the Conservatives are consistently able to scrape together a plurality and govern as a minority.

Admittedly, there is a big difference between a merger and a coalition (and a lesser difference between a Liberal-NDP coalition and a Liberal-NDP-Bloc coalition). Some of the apparent vacillation mentioned above comes down to Liberals feeling more comfortable with a series of temporary Parliamentary alliances than with the actual melting down and recombination of major parties. That said, it may be a basic strategic reality that a united right in a first-past-the-post Parliamentary democracy produces the necessity for a united left, if there is to an opposition that can credibly and effectively hold the government to account. It is worth mentioning that Canadian democracy is also dysfunctional in circumstances where the centre-left has such an unchallenged hold on power as to not face any serious risk of being replaced in government.

With Parliament split between the Liberals, NDP, Bloc, and Conservatives, a fall election would probably just produce yet another Conservative minority, followed by a Liberal leadership race. I doubt anyone would be too sad to see Ignatieff go (at least Dion had some original ideas), but this outcome would just be a perpetuation of the status quo.

The two ways out of gridlock seem to be a Liberal-NDP merger/coalition, or electoral reform that introduces some significant measure of proportional representation.

Canada’s climate plans a flop

As discussed in a post of the Pembina Institute’s blog Canada’s record of failure in dealing with climate change continues to worsen. While the government once promised that Canadian emissions would peak forever sometime between 2010 and 2012, they now expect them to rise all across that span.

Policies the government expected to reduce emissions by 52 million tonnes (megatonnes) of CO2 in 2010 are now expected to produce reductions of just 5 megatonnes. Furthermore, the $1.5 billion Clean Air and Climate Change Trust Fund, distributed to provinces in 2007, did not produce the expected 16 megatonne reduction. Now, the government claims it cut emissions by just 0.34 megatonnes, with 3 more to follow by 2015.

These lackluster results, coupled with ever-rising emissions (especially from the oil and gas sector) demonstrate convincingly that Canada just isn’t doing its part on climate change mitigation. Future generations are likely to see this quite correctly as evidence of short-sightedness and irresponsibility.

Friends of Gin & Tonic

Friends of Gin & Tonic is an amusing website that sets out to mock climate change deniers. They describe their mission as: “Self Interest and Climate Change Denial” and elaborate by explaining:

We seek to inform the public of the findings of a handful of amateurs of unrivalled capability (but almost no ‘formal’ climatological expertise) that utterly undermine the so-called ‘scientific consensus’ that the planet is warming and that people are causing it. This ‘consensus’, the biggest scientific fraud in history, has been foisted on a gullible public by a politico-scientific elite intent on a single world government with themselves, via control of the United Nations, at its head. Exercising merciless control of the scientific literature by requiring that published work be consistent with such piffle as observations, physical principles, and mathematical models, this evil clique tries to suppress the promulgation of any alternative view. Small fringe groups like our sister organization the Friends of Science are thus reduced to using right-wing blogs, opinion columns of like-minded newspapers, and guerrilla publicity stunts at international meetings to promote their message.

Mockery is certainly part of the set of things richly deserved by climate change deniers, though it is not an adequate mechanism for countering their efforts in and of itself.

They came to my attention via DeSmogBlog.

The credit crunch, bailouts, and moral hazard

Why did governments bail out failing financial institutions?

They said it was because banks and insurance companies were so interconnected with the rest of the economy that, if they failed, they would cause a cascade of other failures. If the banks went broke, firms that actually have sound businesses would fall as well. That supposedly risked turning the credit crunch into a general depression.

Assuming this argument is correct, the natural question is what we should do to eliminate that vulnerability, termed ‘systemic risk’ by economists. It is as though we are mountain climbers attached by a tether to the banks. When they start to slip, we need to save them, in order to keep from being pulled over ourselves. Once we have done that, however, we need to start thinking about how to get rid of tether.

According to the argument that politicians are making, we got dragged to the edge of the cliff this time. To experience that and not think seriously about how to get ourselves untethered is stupid and irresponsible.

1) Make banks smaller

No single bank should be large enough that its collapse could threaten the economy as a whole. Banks should be small enough to fail.

2) Make finance more boring

Get rid of complex new products like collateralized debt obligations and credit default swaps. Treat new financial products like new pharmaceuticals, with the onus on those developing them to show that they are safe, and with tough oversight and regulation.

These things seem to spread risk around in the financial system in ways that make it possible for relatively minor players (even non-banks) to really screw things up.

3) Separate the safe and risky sides of banking

There should be two sorts of banks.

The first sort will take deposits and make very safe loans, like well-secured mortgages or loans to businesses with a strong plan for paying them back. These banks should be insured, so that if they fail the depositors don’t lose their money.

These banks should be allowed to call themselves ‘safe banks’ or ‘guaranteed banks’ or something similar, so it is clear to everybody that they are in a special category that excludes the second type.

The second sort can basically do whatever they like. They can invest in all sorts of unusual financial instruments, and try to make profits. When they fail, their depositors get nothing. The only things they cannot do are get too big (see point 1) or sell products that threaten the system (see point 2).

The government loves to boast about how well Canada weathered the financial crisis. The basic reason for that seems to be how boring our banks were forced to remain, as the result of heavy regulation. The places with laissez faire regulatory approaches – like the United States, Ireland, and Iceland – are the ones that have had the most to fear from the credit crunch.

4) Accept the drawbacks

This plan has a number of drawbacks.

First, it might make the financial system less efficient at allocating capital. That’s what banks claim is their value added to society: they match up people who have wealth but no ideas for using it productively with people with ideas and talents, but not enough money.

Making the financial industry safer would reduce returns for savers, and reduce the financing opportunities for firms and entrepreneurs. We might be turning a Ferrari into a Volkswagen, but there are good reasons to do so. For one, it is better to ride in a Volkswagen at 90 km/h than in a Ferrari that goes 120 km/h but sometimes explodes and kills everyone inside. For another, banks and bankers will always have the financial means to manipulate politicians. They are well placed to get a good deal for themselves, whereas the general public is in a weaker position. Since there is a built-in bias in politics towards making things easier for the rich, having some special protection for the general welfare of the population seems justified and appropriate.

Second, making the system safer will make it harder for poor people to get credit. The safe banks won’t offer mortgages to people who are likely to default on them, and the risky banks are likely to change an arm and a leg for them. That said, it was probably always a fantasy for people of modest means to buy big houses in cities with overpriced property markets. Also, by reducing the speculative froth in real estate markets, the approach outlined here could end up helping such people in the long run.

That being said, I think a plan basically resembling this one is worthwhile. Most importantly, it would largely eliminate the systemic risk which we are creating right now by bailing out the institutions that have been the least responsible, because of the threat they pose to everyone else. What that approach will ultimately produce is another, larger crisis.

Of course, this is all a pipe dream. Politicians don’t have the bravery or far-sightedness to do any of this, and bankers are clever enough and rich enough to convince them and bribe them into leaving them basically alone. Besides, that next crisis will probably happen when another lots of politicians are in charge, and those who organized today’s bailouts are occupying well-paid seats on the boards of the banks they rescued.
Fair Vote Canada conference

In Canada, our First Past the Post voting system strongly favours the most popular parties and those (like the Bloc) that have concentrated regional appeal. Parties with a good chunk of popular support, but for which it is not concentrated in particular ridings, are excluded from Parliament.

Many proposals have been brought forward to address that issue. For those interested in the topic and living in Ottawa, this Saturday’s Fair Vote Canada 2010 Annual Meeting and Conference may be of interest. It is happening on campus at the University of Ottawa, between 8:30am and 5:00pm. Registration is $35, or $10 for students.

2010 Arctic sea ice

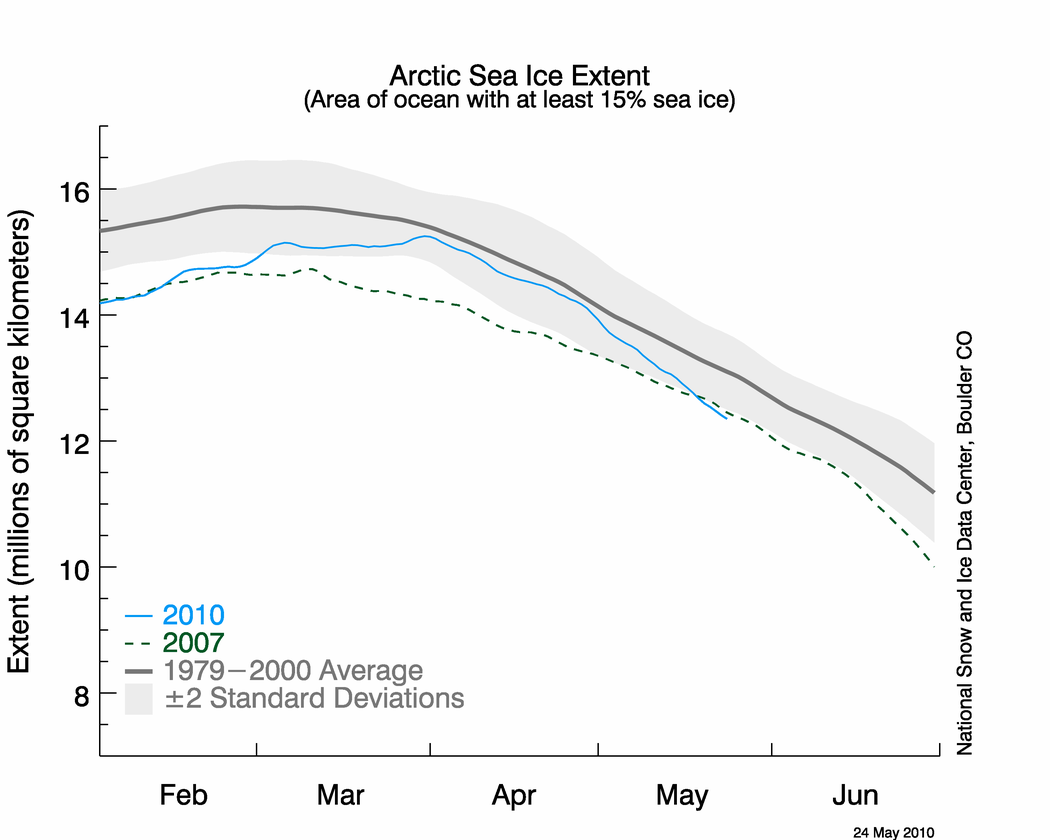
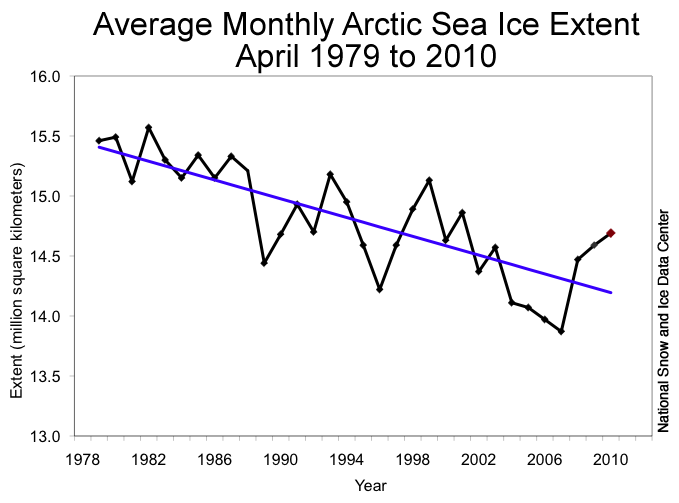
The extent of Arctic sea ice has dipped below where it was at this time of year in 2007, the worst year recorded for sea ice. Within the next few months, we will see whether it goes on to set a new record low. If so, perhaps it could be the sort of dramatic event that drives people to take climate change more seriously.

It is important to understand that the maximum extent of sea ice during the winter is a less important climatic indicator than the minimum extent in summer. The Arctic is always going to be cold and dark in the winter, when it is hardly receiving any sunlight. As a result, at least a thin layer of ice will form, establishing a large extent of frozen ocean. What is vanishing is the multi-year ice, which endures from year to year. Climate deniers trumpeted how the maximum extent of ice this year was close to the 1979 to 2000 average, yet the major trend in ice extent and volume is ever downwards.

If the Arctic ends up ice-free in the summer, there will be numerous consequences. Species that depend on sea ice – including narwhals, seals, and polar bears – will be threatened. Also, migration between the Pacific and Atlantic will likely allow the emergence of invasive species. Because losing summer sea ice means losing a big white sheet that reflects sunlight back into space, it would also cause further warming.

Emissions standards for trucks

In a piece of good news, the Canadian and American governments are rolling out new emissions standards for heavy vehicles, “including full-sized pickup trucks, delivery vehicles, buses, freight vehicles, service trucks, garbage trucks, dump trucks and tractor trailers.”

Trucking is one of the fastest growing causes of greenhouse gas emissions in North America:

The emissions from heavy trucks represent 6 per cent of Canada’s total greenhouse gas emissions. They have been increasing more rapidly than emissions from any other source and grew by 63 per cent from 1990 to 2007 as compared to 26 per cent growth in overall Canadian emissions for the same period.

While regulating efficiency sector by sector risks being more costly than driving economy-wide reductions with a carbon tax, it is nonetheless a welcome measure. Hopefully, the efficiency improvements driven by these new regulations will actually reduce emissions, and not increase them via the rebound effect, by reducing the cost of trucking.

Probably the best Canadian banking setup

A while ago, I abandoned the Bank of Montreal due to their excessive fees. Really, most Canadians have no reason to be paying fees of any sort for most of their financial needs. I have found the following trio to be convenient and well matched to my needs:

1) Day-to-day banking: President’s Choice Financial

Free chequing and savings accounts, free Interac transactions, free cheques, and free use of CIBC bank machines – PC Financial acts as the clearing house for my basic banking. Pay gets directly deposited in, and I pay bills electronically there. My monthly rent cheque is also provided free of charge by them, including PDF versions of the endorsed cheques that can be accessed online. They never send me annoying paper statements.

They don’t have as many bank machines as some of Canada’s other banks do, but I think that is more than made up for by unlimited free Interac transactions.

2) Savings: ING Direct

With no fees and relatively high interest rates, I think ING Direct is the best choice in Canada for many savings purposes. I have investment savings accounts with them (mostly tax free, but one ordinary one for when my TFSA contribution is maxed out), GICs, and index tracking mutual funds. The 1% MEF on the mutual funds is a bit high, but ING doesn’t charge any fees for buying and selling. ING also provides no fee retirement savings options, which can include any mixture of investment savings accounts, GICs, and mutual funds under an RSP umbrella.

It is easy to transfer money electronically between ING and PC Financial, with about a three day lag in either direction. ING pays interest on the days during which you are waiting for funds to clear.

If anyone is planning to join, give them the ‘Orange Key’ 14534017S1 and they will give you (and me) $25.

In the long run, those wanting to make investments in index tracking funds are probably better off just buying the Vanguard funds best matched to their investment strategy directly. Though such an approach, it is possible to get an MEF of under 0.5%, though it requires paying one-off trading fees and dealing with a bit of inconvenience.

3) Credit card: Citibank Enrich Mastercard

No fees, with 1% cash back. This is the best credit deal I have been able to find in Canada, and I use it for routine payments like internet, my cell phone, zip.ca, and insurance. Just make sure to pay it off in full at the end of every month.

If you spend a lot of money at a particular store, it may be worth getting one of their branded credit cards. That said, many of them are less generous than the Citibank offering. The Sears card, for instance, gives 1% cash back, but it can only be used in blocks to get gift certificates from particular retailers. Citibank just gives you the cash once a year.

Note: The former Citibank Enrich MasterCard is no longer available, since CitiBank got rid of its Canadian credit card operations. The same basic card can now be acquired from CIBC. They call it the ‘Dividend One’ MasterCard. It provides 1% cash back on all purchases, and has no annual fee.

Conclusions

With this this trio, you get most of the financial services ordinary Canadians need while earning decent interest rates, getting 1% back on credit card purchases, and paying no fees whatsoever. Those who are paying $10+ per month for the privilege of having chequing and savings accounts, $0.50 a pop for Interac transactions, or $50+ per year for 1% back on their credit cards should contemplate making some changes.

Are there any even better deals out there that I haven’t found yet?

[Update: 10 September 2010] ING is rolling out a chequing service in Canada, called ‘THRiVE’. Like PC Financial, there are no monthly fees. ING also pays interest on chequing accounts and offers your first chequebook free. Whereas PC Financial allows free use of CIBC machines, the ING service allows free use of machines on the Exchange Network. This mostly seems to consist of local credit unions. All told, I think the PC Financial offering is better.

[Update: 10 November 2010] I have written an open letter to both of these banks encouraging them to stop investing in fossil fuel projects.